

Glep vs. Credit One Bank
Credit One Bank is a consumer credit card issuer with savings and CDs. Glep is banking, cards and spend management built for businesses that own and operate real estate.
Features: Glep compared with Credit One Bank
Real estate & entities
Multi-entity management
Every LLC from one login, funds and records separated per entity
Account per LLC, sub-account per property
Each with its own routing and account number, so deposits, draws and reserves never mix
Property-level tracking
Every card purchase, ACH, wire and RTP payment tagged to a property, deal or unit as it happens
Aida deal analysis
Rehab cost, ARV, NOI, purchase price, red flags and an offer letter from an address
Aida on transactions
Categorizes every transaction, matches receipts, flags unusual charges, answers questions by property
Team access scoped per entity
Custom roles and entity-level visibility, included free
Banking & spend
Business banking
Checking and savings through Core Bank, Member FDIC
Unlimited cards
Physical and virtual Visa cards with daily, weekly or monthly limits, merchant locks, freeze and terminate
Contractor cards with a hard cap
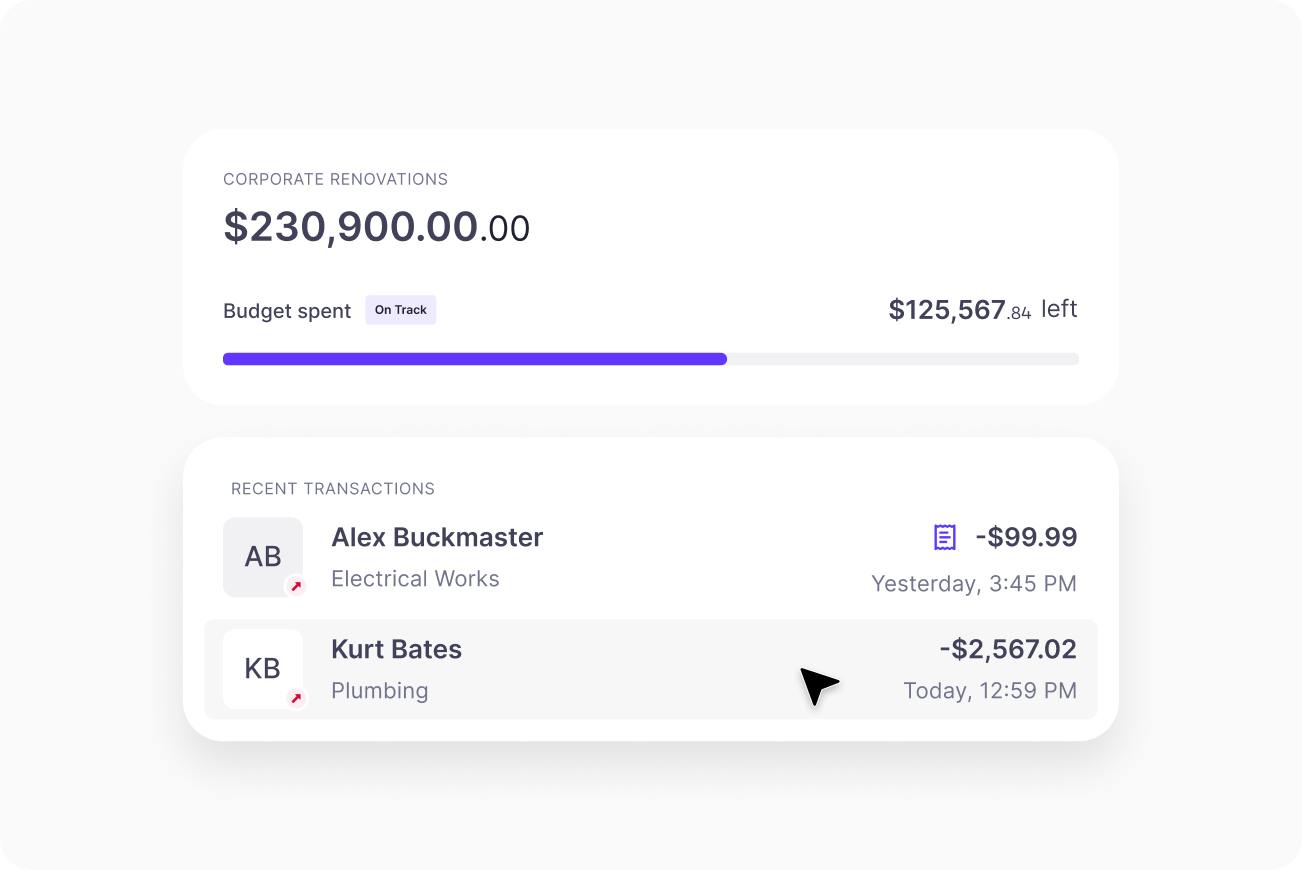
The card stops working when the project budget is spent
Approvals and expense policies
Approval workflows, parallel approvers and receipt rules, included free
Same-day ACH and wires at $0, plus RTP and FedNow
$0 same-day ACH and domestic wires; RTP and FedNow available; 3% FX fee on international card transactions
Mobile app
Issue, freeze and terminate cards, capture receipts and approve spend from the job site
Pricing
Free, no per-user fee
$0 monthly fee, no credit card to start. 3% FX fee on international card transactions
Credit One Bank is a trademark of Credit One Bank, N.A. Credit One Bank products are as published at creditonebank.com on September 25, 2026 and are subject to change.
Why real estate businesses choose Glep
What changes when the platform is built around properties, deals and LLCs.
Get started with GlepEnter an address and Aida estimates rehab cost, ARV and NOI, recommends a price, flags red flags and drafts the offer. After closing, Aida categorizes every transaction, tags it to the property and matches the receipt to the vendor, job and GL code. Credit One Bank issues a credit card; it has no view of a business, let alone a deal.
Credit One Bank publishes no business checking, business cards or spend tools. Glep is business banking through Core Bank, Member FDIC: one account per LLC, a sub-account per property with its own routing and account number, team access scoped per entity, all free.
A card per contractor or project with a hard budget cap that stops the card when the budget is spent. Unlimited cards, limits by day, week or month, merchant locks, freeze and terminate from the mobile app, and same-day ACH and domestic wires at $0, plus RTP and FedNow. Credit One Bank publishes consumer credit cards only: no business cards, no project caps, and no business payment rails at all.
Further comparisons with Credit One Bank and other alternatives to it
Glep vs Capital One
Capital One is a national bank with Basic and Enhanced business checking and Spark business cards. See how Glep compares.
Learn more
Glep vs American Express
American Express offers business cards and a business checking account with rewards. See how Glep compares.
Learn more
Glep vs Chase
Chase is a national bank with tiered business checking, branches and Ink business credit cards. See how Glep compares.
Learn moreFrequently asked questions about Glep and Credit One Bank
Credit One Bank is a consumer credit card issuer with cash back and credit-building cards, plus high-yield savings and certificates of deposit; it publishes no business checking, business cards or spend management. Glep is banking, cards and spend management for real estate businesses, through Core Bank, Member FDIC. Every LLC gets its own account and every property its own sub-account with a unique account number, Aida tags every transaction to a property or deal as it happens and analyzes deals before you buy them, and contractor cards carry hard budget caps. Glep is free, with $0 same-day ACH and domestic wires, plus RTP and FedNow, and a 3% FX fee on international card transactions.
Not as published on creditonebank.com on September 25, 2026: its product index lists consumer credit cards, savings and CDs. Glep is $0 with no monthly fee, no per-user fee, $0 same-day ACH and domestic wires, plus RTP and FedNow, and a 3% FX fee on international card transactions.
You can spend on one, and many operators do, but the card knows nothing about your LLCs or properties and the money still sits in a separate bank account. On Glep, every LLC lives under one login with its own account, cards and records, each team member sees only the entities you give them, and every property gets a sub-account with its own account number, all free.
Yes. A virtual or physical card for the contractor, capped at the project budget, locked to specific merchants, terminated in a click when the job ends. Credit One Bank publishes consumer credit cards alongside consumer savings and CDs; it publishes no business account and no contractor card, so there is nothing on its side to set this against.
Glep works upstream of your ledger: transactions arrive categorized and tagged to a property, so your accountant's software receives clean data and you keep it. Credit One Bank offers no property-level tracking, no categorization and no published business account, so there is nothing on its side that feeds a ledger at all.
Yes. The Glep app runs on iOS and Android with receipt capture at the point of spend, card issue, freeze and terminate, and approvals, each person scoped to their entities. Credit One Bank's app is a consumer app for consumer cards; with no business account published, there is no team to give access to.
No, and there may be nothing to close: Credit One Bank publishes consumer credit cards alongside consumer savings and CDs, not a business account, so for most operators this is not a switch but a first business account. Open a Glep account online with your US business entity and EIN, add each LLC, open a sub-account per property and issue cards. Keep the consumer card if it is useful to you personally; it was never carrying the business.
If your business is a set of properties held in a set of entities, Glep is built around that structure: an account per LLC, a sub-account per property, Aida tagging every transaction to the property it belongs to, and contractor cards that stop at the budget. Contractors and developers get the same structure for projects, draws and crews, and pay subs by same-day ACH or wire at $0, or by RTP or FedNow. If your business is outside real estate but runs money across several entities, projects or vendors, Glep gives you multi-entity management, entity-scoped team access, sub-accounts with unique account numbers, approval workflows and unlimited cards on the free plan, with no personal credit card standing in for a business finance stack. Start with one property or one project and move the rest on your own schedule; there is no contract and no lock-in.